Mortgage and Home Loans in the USA: Complete 2026 Guide
Mortgage and Home Loans Mortgage and Home Loans in the USA: A Complete Guide for First-Time Homebuyers in 2026
Buying a home is one of the biggest financial decisions most people make during their lifetime. For many Americans, purchasing a property requires financial assistance through a mortgage or home loan. Understanding how these loans work
Home Loans in USA can help buyers make smarter decisions, manage their budgets, and avoid unnecessary financial stress.
Whether you are purchasing your first home, upgrading to a larger property, or refinancing an existing mortgage, learning about different financing options is an important first step.
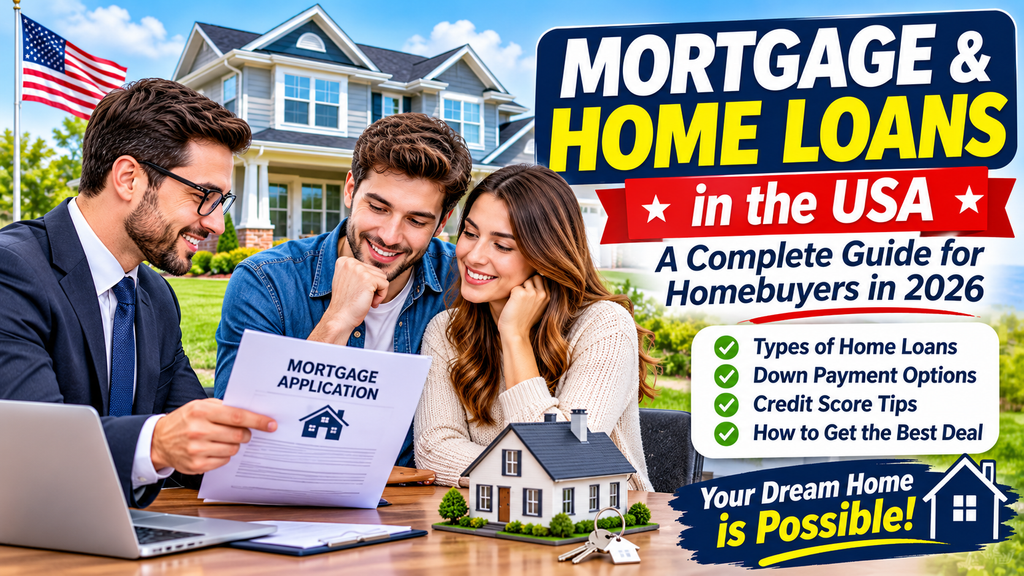
In this guide, we will explain how mortgage loans work in the United States, explore popular loan types, discuss eligibility requirements, and share practical tips for finding a mortgage that fits your financial situation.
What Is a Mortgage Loan?
A mortgage is a type of loan that allows individuals to purchase real estate without paying the entire property price upfront.
The borrower receives money from a lender and agrees to repay it over an agreed period, usually through monthly payments. The property serves as collateral for the loan, meaning the lender may have the right to begin foreclosure proceedings if the borrower fails to meet the repayment obligations.
A typical mortgage payment may include several components:
- Principal: The original amount borrowed from the lender.
- Interest: The cost of borrowing money.
- Property Taxes: Local taxes associated with property ownership.
- Homeowners Insurance: Coverage that protects the property against certain risks.
- Mortgage Insurance: Additional protection that may be required for certain loan arrangements.
Understanding these expenses is important because the monthly mortgage payment is not always limited to the loan principal and interest.
Different Types of Mortgage Loans in the USA
American homebuyers can choose from several mortgage options. Each loan type has different eligibility requirements, costs, and benefits.
1. Conventional Mortgage Loans
Conventional mortgages are loans that are not directly insured or guaranteed by the federal government.
They are commonly offered by banks, credit unions, and mortgage companies. Some conventional loans follow guidelines established by Fannie Mae and Freddie Mac.
Borrowers with strong credit histories and stable incomes may find conventional financing attractive.
Depending on the loan program, borrowers may qualify with a down payment below 20%. However, private mortgage insurance (PMI) is generally required when the down payment is less than 20% on a conventional mortgage.
2. FHA Home Loans
Federal Housing Administration (FHA) loans are designed to make homeownership more accessible to eligible borrowers.
These mortgages are insured by the FHA and are offered through approved lenders.
Some important features include:
- Down payments as low as 3.5% for borrowers meeting applicable credit requirements.
- More flexible credit qualification guidelines than many conventional programs.
- Availability for eligible first-time and repeat homebuyers.
- Mortgage insurance requirements.
FHA loans can be useful for people who have limited savings or are building their credit history.
3. VA Mortgage Loans
VA home loans are available to eligible veterans, active-duty service members, and certain surviving spouses.
These loans are backed by the Department of Veterans Affairs and are offered by participating private lenders.
Depending on eligibility and lender requirements, VA loans may offer:
- No required down payment in many cases.
- No monthly mortgage insurance.
- Competitive financing terms.
- Flexible qualification options.
Eligible borrowers should review the VA’s official guidelines before applying.
4. USDA Home Loans
USDA loans are designed to support eligible homebuyers purchasing properties in qualifying rural and suburban areas.
These mortgages are backed by the United States Department of Agriculture.
Some USDA loan programs offer zero-down-payment financing for eligible borrowers. However, property location, household income, occupancy, and other program requirements apply.
They can be worth exploring for buyers interested in purchasing homes outside major metropolitan areas.
How Much Mortgage Can You Afford?
Before applying for a home loan, it is important to understand how much you can comfortably afford.
A lender may approve you for a certain loan amount, but that does not automatically mean you should borrow the maximum available amount.
Your monthly budget should account for several expenses, including:
- Monthly income after taxes.
- Existing credit card and loan payments.
- Property taxes.
- Homeowners insurance.
- Utilities and maintenance.
- Emergency savings.
- Other household expenses.
For example, someone earning $7,000 per month may have different borrowing capacity depending on existing debts, savings, credit history, and living expenses.
A mortgage affordability calculator can help estimate potential monthly payments before contacting lenders.
What Credit Score Do You Need for a Mortgage?
Your credit score is one of the factors lenders consider when reviewing a mortgage application.
A stronger credit profile may help you qualify for more favorable loan terms, although approval also depends on income, debt, assets, loan type, and other requirements.
Different mortgage programs have different credit guidelines.
For example, FHA borrowers may qualify with a credit score of 580 or higher for the program’s minimum 3.5% down payment, subject to applicable requirements. A score between 500 and 579 may qualify with a down payment of at least 10%, although individual lenders can impose stricter standards.
Conventional and other mortgage programs have their own qualification rules.
Before applying, consider checking your credit reports for incorrect information, paying bills on time, and reducing outstanding credit card balances.
How Much Down Payment Do You Need?
A down payment is the amount of money a buyer contributes toward purchasing a property.
Many buyers believe they must save 20% of the property’s purchase price before buying a home. However, that is not always necessary.
Some mortgage programs allow eligible buyers to purchase a property with a smaller down payment.
For example:
- Certain conventional programs allow down payments as low as 3%.
- Eligible FHA borrowers may qualify with 3.5% down.
- Eligible VA and USDA borrowers may qualify for zero-down-payment options.
A larger down payment can reduce the amount borrowed and may lower monthly payments.
However, buyers should also maintain enough savings for closing costs, moving expenses, repairs, and unexpected financial situations.
Fixed-Rate vs. Adjustable-Rate Mortgages
Another important decision is choosing between a fixed-rate mortgage and an adjustable-rate mortgage.
Fixed-Rate Mortgage
A fixed-rate mortgage maintains the same interest rate throughout the agreed loan term.
This provides predictable principal and interest payments, making long-term budgeting easier.
It may be suitable for buyers who prefer payment stability and plan to remain in their homes for many years.
Adjustable-Rate Mortgage (ARM)
An adjustable-rate mortgage generally starts with an initial interest rate that remains fixed for a specified period.
After that period, the rate can change according to the loan agreement and a specified financial index.
An ARM may offer a lower initial rate in some circumstances, but future payments can increase when interest rates adjust.
Buyers should carefully review adjustment periods, rate caps, and potential payment changes before choosing this option.
Documents Required to Apply for a Mortgage
Mortgage lenders generally require documentation to verify an applicant’s financial position.
Although requirements vary, common documents include:
- Government-issued identification.
- Recent pay stubs.
- W-2 forms or tax returns.
- Recent bank statements.
- Employment information.
- Details of existing loans and debts.
- Information about available down payment funds.
Self-employed applicants may need additional tax returns, business financial statements, or other income documentation.
Providing complete and accurate information can help prevent unnecessary delays during the application process.
How to Get the Best Mortgage Deal
Finding the right mortgage requires more than choosing the first lender that approves your application.
Here are some practical steps that can help you compare available options.
Compare Multiple Lenders: Contact banks, credit unions, and mortgage companies to compare their loan offers.
Review Annual Percentage Rate (APR): APR provides a broader picture of borrowing costs because it includes the interest rate and certain loan fees.
Understand Closing Costs: Ask lenders for a Loan Estimate to review estimated interest rates, fees, monthly payments, and other expenses.
Improve Your Credit Profile: Paying bills on time and reducing outstanding debt may improve your financial position.
Avoid Unnecessary New Debt: Taking out additional loans before closing may affect your mortgage approval.
Consider Your Long-Term Plans: Think about how long you expect to own the home before selecting a mortgage structure.
Frequently Asked Questions About Mortgage and Home Loans
Can I buy a house with no down payment in the USA?
Yes. Eligible borrowers may qualify for certain VA or USDA mortgage programs without a required down payment. Other financing options may require a minimum contribution.
How long does mortgage approval take?
The timeline varies depending on the lender, property appraisal, documentation, underwriting, and other factors. Many mortgage transactions take several weeks, but some may take longer.
Is it better to choose a 15-year or 30-year mortgage?
A 15-year mortgage generally has higher monthly payments but can reduce total interest costs. A 30-year mortgage usually offers lower monthly payments, although total interest paid may be higher.
The better choice depends on your budget and long-term financial goals.
Can I refinance my existing mortgage?
Yes. Homeowners may refinance to change their interest rate, loan term, monthly payment, or loan structure. Approval depends on the lender’s requirements and the borrower’s financial circumstances.
Do first-time homebuyers receive special mortgage benefits?
Some first-time homebuyers may qualify for state, local, or federal assistance programs. These can include down payment assistance, closing cost support, or specialized mortgage options.
Final Thoughts
Choosing the right mortgage is an important part of achieving homeownership in the United States. From conventional and FHA loans to VA and USDA financing, buyers have several options to consider.
Before making a decision, evaluate your financial situation, understand the total cost of borrowing, compare multiple lenders, and review all loan documents carefully.
Remember that the lowest advertised interest rate does not always represent the cheapest mortgage. Fees, mortgage insurance, repayment terms, and future financial flexibility also matter.
With proper research and careful financial planning, you can choose a home loan that supports your homeownership goals while keeping your long-term finances under control.
Disclaimer: This article is for informational and educational purposes only. It does not constitute financial, legal, or mortgage advice. Mortgage eligibility, interest rates, fees, and program requirements vary by lender and borrower. Consult a qualified mortgage professional before making financial decisions.